Category: Home Social Stocks

  • Social Stock Exchange: A Game-Changer for CSR in 2026

    Social Stock Exchange: A Game-Changer for CSR in 2026

    India’s Social Stock Exchange (SSE) is not a new bourse like NSE or BSE. It is a dedicated segment within these exchanges where not‑for‑profit organisations (NPOs) can raise money for social projects through listed instruments. The idea: use the familiar machinery of the stock market to route philanthropic and CSR capital, while improving transparency, governance and accountability.

    What problem is it trying to solve?
    For years, companies mandated to spend on Corporate Social Responsibility (CSR) under Section 135 of the Companies Act have channelled funds via grants, trusts, foundations and government funds. But there was no regulated, market‑like platform that could:

    • Vet social enterprises in a standard way,
    • Disclose how money is being used, and
    • Let multiple funders participate in the same project with clear terms.

    SEBI’s SSE, operational since 2023, was built to fill this gap.

    How does it work?

    Eligible NPOs register on the SSE and issue Zero Coupon Zero Principal (ZCZP) instruments. These are not typical bonds:

    Zero coupon: Investors get no interest.

    Zero principal: There is no repayment of the principal amount.

    In effect, a ZCZP is a donation structured as a listed security. The money raised must be used for the NPO’s stated social projects, with disclosures on the exchange platform.

    What changed in 2026?
    The big shift came on May 27, 2026, when the Ministry of Corporate Affairs (MCA) amended the Companies (CSR Policy) Rules, 2014 and Schedule VII of the Companies Act. Two changes matter most:

    1. ZCZP on SSE is now an eligible CSR activity
    • A new item (xiii) was inserted into Schedule VII: “Subscription to zero coupon zero principal instruments on Social Stock Exchange.”

    2. A 10% cap and an exemption

    • Companies can now route up to 10% of their total CSR expenditure in a financial year into ZCZPs listed on SSE.
    • For this slice, they are exempt from conducting a separate impact assessment, which has been a major administrative burden for CSR teams.

    In parallel, SEBI eased some SSE norms in April 2026, including extending the NPO registration window and lowering the minimum subscription threshold, to make it easier for credible NPOs to come in and for issues to succeed.

    Why should companies and NGOs care?
    For companies, the SSE route offers:

    • A regulated channel to deploy part of CSR funds, with exchange‑style disclosures.
    • Lower compliance load for up to 10% of CSR spend, thanks to the impact‑assessment exemption.
    • The ability to co‑fund specific projects alongside other corporates through the same ZCZP issue.

    For NPOs/NGOs, it offers:

    • Access to a national investor base (including retail with demat accounts), not just a few large donors.
    • A structure that can improve credibility and trust, given SEBI’s oversight and disclosure norms.
    • A potential path to scale recurring social programmes with clearer funding visibility.

    Where is it headed?
    Despite the policy push, the government has not carried out any assessment on how much the ZCZP route will actually boost institutional CSR inflows, Parliament was told in August 2026. The key test now is adoption: whether CSR committees are comfortable routing part of their budgets through ZCZPs, and whether enough high‑quality NPO pipelines emerge to make the market meaningful.

    Early movers are already testing the model. In August 2026, DEVI Sansthan, an NPO working on foundational literacy, listed on the BSE SSE to mobilise resources for its programmes. Separately, a coalition led by ImpactScale Ventures, with support from NSE, SEBI’s advisory committee and US TIFA, announced a TB‑focused thematic raise on SSE, aiming to help 15+ TB NGOs register and 8–10 list projects to raise around Rs 50 crore via ZCZPs.

    The bottom line
    The Social Stock Exchange does not replace traditional CSR. It adds a regulated, market‑linked option for a slice of CSR money, with the promise of greater transparency and easier compliance for that portion. The 2026 amendments—especially the 10% cap and impact‑assessment exemption—are designed to nudge companies to try the route. Whether SSE becomes a meaningful channel for India’s CSR pool will depend on how quickly credible NPOs list, and how comfortable boards become with this new instrument
  • From pilots to policy: what DEVI Sansthan’s Ladakh MoU tells us about social finance

    From pilots to policy: what DEVI Sansthan’s Ladakh MoU tells us about social finance

    S Eldee

    The real test of India’s social sector is not how many pilot projects we can launch, but how many of them survive long enough to become policy. For years, the story has been familiar: a promising NGO runs a small, donor‑funded experiment in a few districts; evaluations look good; then the money runs out, the team shrinks, and the model remains a footnote in a PowerPoint.

    The recent trajectory of Lucknow‑based DEVI Sansthan — from a modest Zero Coupon Zero Principal (ZCZP) issue on the BSE Social Stock Exchange to a three‑year Memorandum of Understanding with the Ladakh administration — hints at a different path: one where social finance, if designed well, can help turn pilots into public programmes.

    DEVI’s journey began, in market terms, as a niche experiment. In June–July 2026, the organisation listed on the BSE Social Stock Exchange, raising about Rs 1.10 crore through ZCZP instruments priced at Rs 1 each, with a minimum ticket of just Rs 1,000. The pitch was simple: investors would not get interest or principal back; instead, their money would fund foundational literacy and numeracy (FLN) programmes for tens of thousands of children in government schools, with impact tracked and reported under SEBI’s social exchange framework.

    For a sector used to CSR cheques and foundation grants, this was novel: a regulated, transparent, retail‑accessible channel for “human returns” rather than financial ones.

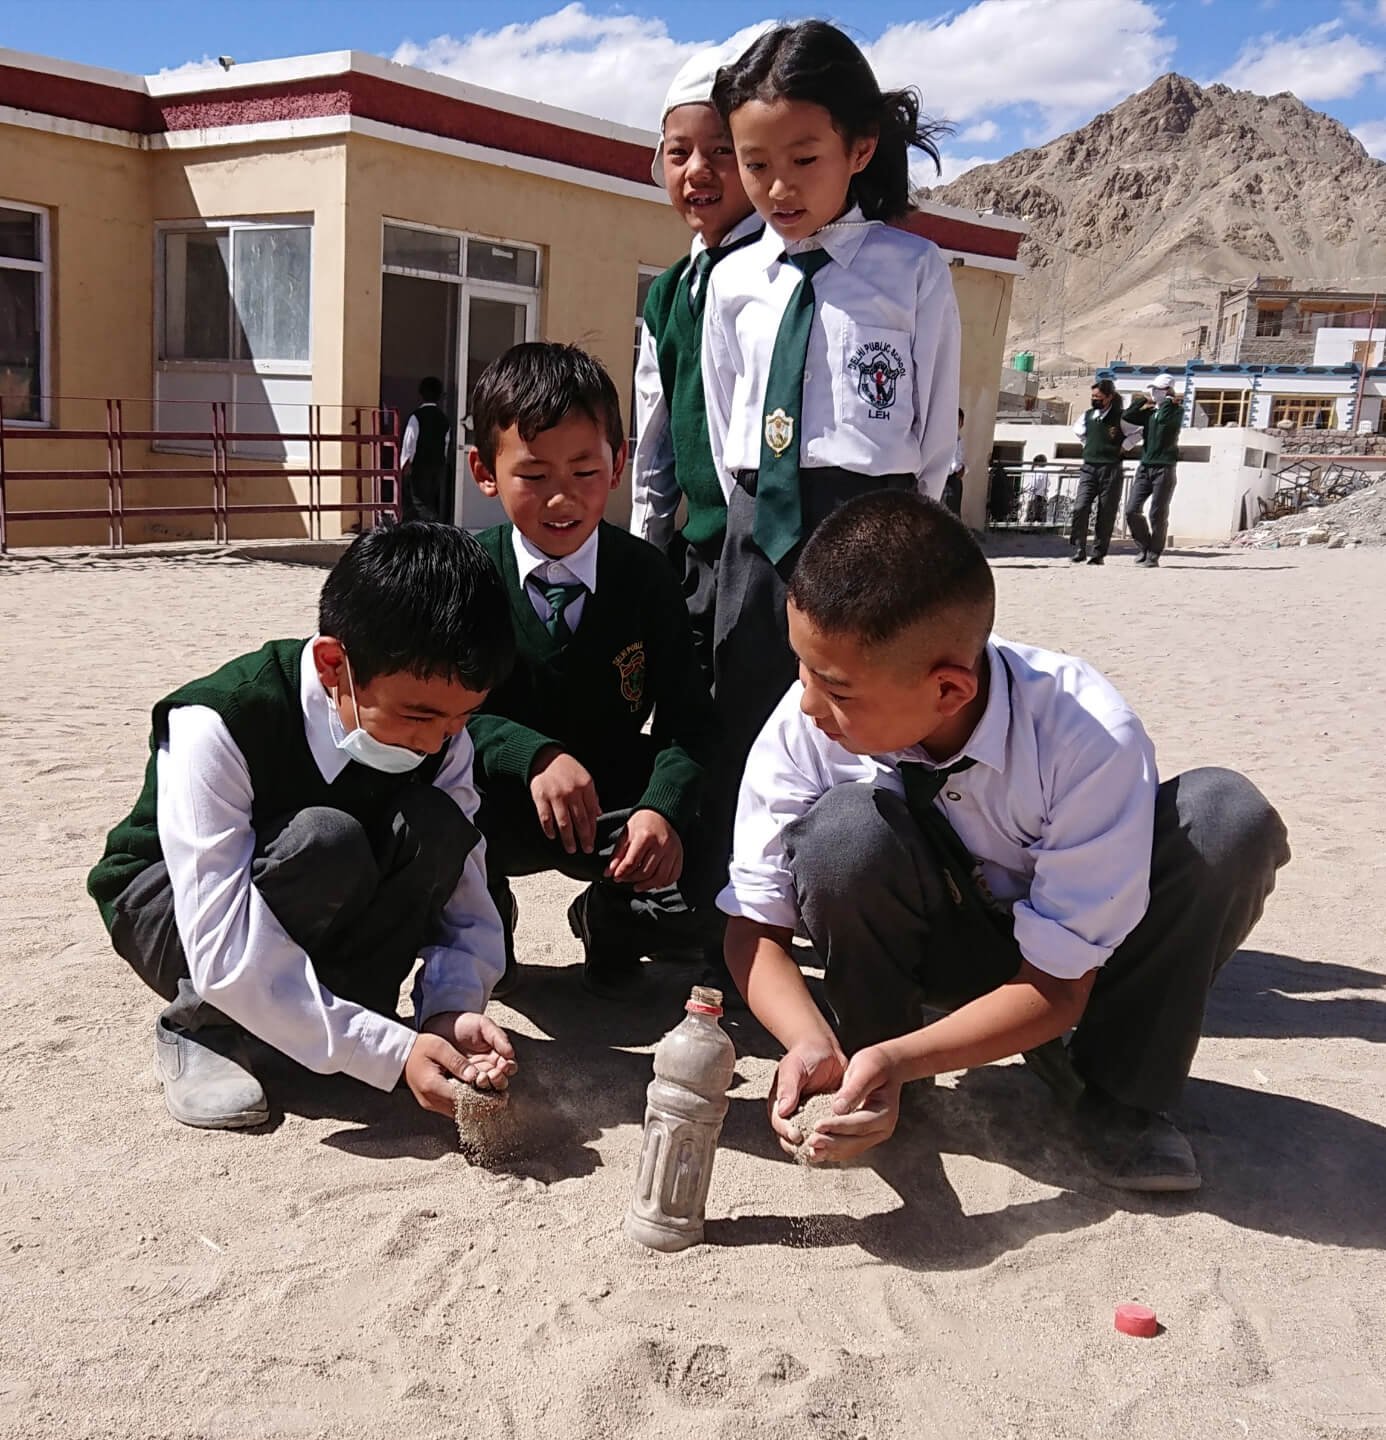
    What makes the Ladakh MoU, signed on 11 August 2026, significant is not just that a union territory chose an NGO partner, but that it chose one that had already tested its model in the market. Under the three‑year agreement, DEVI Sansthan will work with Ladakh’s School Education Department to strengthen FLN across the region, aligning with the national NIPUN Bharat mission’s goal that every child attain grade‑level reading and arithmetic by Class 3. In effect, capital raised through the Social Stock Exchange is being leveraged into a multi‑year, government‑backed scale‑up — exactly the transition that India’s education and social sectors desperately need.

    This sequence — SSE issue first, government MoU later — matters for three reasons.

    First, it shows that social stock exchanges can do more than raise money; they can de‑risk scale. When a government signs a multi‑year contract with an organisation that has already disclosed its finances, governance and impact metrics on a regulated platform, it reduces the information asymmetry that often stalls public procurement of social services. The SSE listing acts as a form of due diligence that is visible to citizens, donors and officials alike.

    Second, it begins to solve the pilot paradox. India does not lack successful education pilots; it lacks mechanisms to move them from “project mode” to “system mode”. By allowing NPOs to raise patient, no‑repayment capital for specific outcomes, and then letting governments layer on longer‑term contracts, the SSE framework can help convert proof‑of‑concept into proof‑of‑scale. DEVI’s Ladakh deal is still early, but it is a template: market‑tested model, transparent reporting, then public adoption.

    Third, it offers a new narrative for CSR and philanthropy. Instead of one‑off grants that vanish after a news cycle, corporate and individual investors can back organisations that are building towards government partnerships. The “exit” is not an IPO or acquisition, but a policy uptake — the moment when the state says: this works, we will fund it at scale. That is a far more durable form of impact than any annual report claim.

    Of course, caution is necessary. A single MoU does not prove a trend; Ladakh’s unique administrative structure may not replicate easily in larger, more complex states. There are also risks: over‑financialisation of the social sector, excessive focus on easily measurable metrics at the cost of deeper learning, and the possibility that only a few well‑advised NGOs can navigate SEBI’s framework while smaller, grassroots groups are left behind. The Social Stock Exchange must remain a tool for mission, not a badge for marketing.

    Yet, the direction is clear. If India is serious about fixing foundational learning, health, nutrition and livelihoods, it cannot rely on perpetual pilots funded by restless donors. It needs mechanisms that allow successful models to graduate into public systems with clarity on cost, quality and accountability. DEVI Sansthan’s path — from a Rs 1.10 crore ZCZP issue to a three‑year government partnership in Ladakh — is a small but telling sign that this graduation is possible.

    The question now is whether other states, departments and donors are watching closely enough to replicate it.

  • No assessment done on ZCZP instruments boosting CSR funds: Govt

    No assessment done on ZCZP instruments boosting CSR funds: Govt

    The government has not carried out any assessment on the extent to which the newly introduced “Subscription to zero coupon zero principal (ZCZP) instruments on Social Stock Exchange” is likely to boost the inflow of institutional capital into the social sector, Parliament was informed on Monday.

    In a written reply to the Lok Sabha, Minister of State for Corporate Affairs Harsh Malhotra said, “No such assessment has been conducted by the ministry.”

    The Ministry of Corporate Affairs, through a notification dated May 27, 2026, widened the ambit of Schedule VII of the Companies Act, 2013, by introducing a new item — “Subscription to zero coupon zero principal instruments on Social Stock Exchange” — as an eligible Corporate Social Responsibility (CSR) activity.

    As per the amendment, a CSR-mandated company cannot subscribe to ZCZP instruments for more than 10 per cent of its total CSR expenditure for that financial year.

    Malhotra said the move is intended to ease compliance for companies while helping not-for-profit organisations raise funds for public welfare projects “in a transparent and regulated manner.”

    The ZCZP instrument, listed on the Social Stock Exchange, allows companies to channel CSR funds to eligible non-profits without expecting financial returns, aiming to formalise and bring greater transparency to social sector financing.

  • Why India’s finance ministry must unlock ZCZP tax benefit now

    Why India’s finance ministry must unlock ZCZP tax benefit now

    By Eldee

    India’s Social Stock Exchange was conceived as an audacious idea: a marketplace where social impact, not profit, would be the currency of exchange. Three years since its conceptual birth and two years since its first listing, the experiment is showing tentative but real promise. Yet it remains trapped at the threshold of its own potential — held back, ironically, not by a lack of vision or legislation, but by one pending signature from the Finance Ministry on a Section 80G notification.

    The recent MCA amendment of May 27, 2026 is a meaningful step forward. By formally recognising Zero Coupon Zero Principal — ZCZP — instruments as eligible CSR expenditure under Schedule VII of the Companies Act, 2013, the government has given India Inc. a structured, regulated pathway to channel mandatory social spending through verified, listed non-profit organisations on the SSE. Companies may now route up to 10 per cent of their annual CSR expenditure through ZCZP instruments. That is not a trivial number.

    For India’s top 1,000 companies collectively spending over Rs 25,000 crore annually on CSR, 10 per cent represents a potential market of Rs 2,500 crore flowing through a transparent, accountable exchange mechanism. And yet, the number that tells the real story of the SSE today is grimmer: only 10 organisations from a registered pool of over 100 NPOs have successfully raised capital.

    Total capital mobilised, approximately Rs 10,687 crore, sounds large until you recognise how concentrated and slow that mobilisation has been. The Swades Foundation’s landmark Rs 100 crore raise in 2024 was celebrated precisely because it was exceptional — a proof of concept rather than a reflection of the norm.

    The structural reason for this underperformance is not complex. Corporations deploying CSR funds have no tax incentive to route money through ZCZP rather than through direct CSR implementation or conventional Section 80G donations to established charities.

    A ZCZP instrument offers something distinctive — verified social impact reporting, exchange-listed transparency, SEBI oversight, and a cap on project duration of three financial years — but it offers no additional tax benefit over a cheque written to a Prime Minister’s Relief Fund. Until SEBI’s June 2024 proposal to the Finance Ministry is formally notified, the transformative power of the ZCZP architecture remains inert.

    The case for Section 80G parity for ZCZP instruments is not sentimental. It is fiscal and structural. Consider what the instrument actually does. An investing company receives no coupon. It receives no return of principal. The entire invested amount is deployed toward a social project run by a registered, SEBI-supervised, exchange-listed non-profit.

    The company receives, in return, verified impact data — not financial yield. If there was ever an instrument that deserved to be treated as a charitable donation for tax purposes, this is it. The Finance Ministry’s hesitation, nearly two years after SEBI’s formal proposal, is difficult to justify on either revenue or policy grounds.

    Critics might argue that allowing Section 80G deductions for ZCZP purchases could create a loophole — that companies might use the instrument to satisfy both their CSR obligation and claim a separate income tax deduction, effectively double-dipping. This is a legitimate concern and one the Finance Ministry should address through careful drafting, not indefinite delay.

    The solution is straightforward: ZCZP investments can be treated as eligible either for CSR expenditure counting or for Section 80G deduction, but not simultaneously for both.

    SEBI and MCA between them have the regulatory architecture to enforce this distinction. The two regulators have already demonstrated coordination in the May 2026 amendment — extending that coordination to a jointly-drafted Section 80G framework should not be beyond reach.

    What makes the ZCZP architecture genuinely transformative — and worth fighting for — is what it offers beyond tax efficiency.

    Unlike conventional CSR, where impact assessment is often cursory or self-reported, ZCZP instruments come with mandated impact reporting. Any unspent funds at project termination must be transferred to a Schedule VII fund. The NPO must remain listed on the SSE throughout the instrument’s life. These are not trivial compliance conditions; they are the architecture of accountability that India’s CSR ecosystem has long lacked.

    India spends more on mandatory CSR than almost any other country in the world. The 2013 amendment to the Companies Act created a legal obligation that, a decade later, generates tens of thousands of crores in annual social expenditure. But the quality of that expenditure — its traceability, its impact rigour, its freedom from cronyism and tokenism — remains deeply uneven.

    The SSE, and ZCZP specifically, represent the most serious institutional attempt yet to bring capital markets discipline to social spending.

    The 10-organisation statistic is not a failure of the model. It is a market waiting for a signal. Corporate treasury teams, CSR committees, and impact investors are sophisticated actors. They respond to incentives.

    When the Finance Ministry formally notifies Section 80G eligibility for ZCZP instruments — not if, but when — the effect on SSE fundraising activity will be immediate and measurable.

    NPOs registered on the exchange but unable to attract corporate capital will suddenly find themselves competitive. The Swades Foundation story will stop being an outlier and start being a template.

    The MCA’s May 2026 notification has lit the fuse. The Finance Ministry holds the match. The transformative potential of India’s Social Stock Exchange depends on what it decides to do next.

  • A market for good: why the ZCZP instrument could be CSR’s most important reform

    A market for good: why the ZCZP instrument could be CSR’s most important reform

    By Eldee

    For over a decade since the Companies Act of 2013 made Corporate Social Responsibility mandatory, India Inc has wrestled with the same uncomfortable truth: writing a cheque is easy; ensuring it actually changes lives is not. Project selection, implementation partners, monitoring mechanisms, third-party impact assessments — the compliance apparatus around CSR has grown so elaborate that the overhead sometimes rivals the impact. The Ministry of Corporate Affairs’ amendment of May 27, 2026, quietly addresses this problem. It deserves far more attention than it has received.

    The amendment permits companies to deploy up to 10 per cent of their CSR funds into Zero Coupon Zero Principal (ZCZP) instruments issued by eligible Not-for-Profit Organisations listed on the Social Stock Exchange (SSE). The instrument’s name is its entire architecture: no interest, no principal repayment. What a company invests is what a cause receives — in full, with no financial return expected and no capital clawed back at maturity. It is, in economic substance, a structured grant. But in regulatory form, it is a listed, exchange-monitored, disclosure-bound security. That distinction matters enormously.

    Why Companies Should Pay Attention

    India Inc’s annual CSR obligation now hovers around Rs 35,000 crore. A significant portion of that is spent well. But a meaningful share is lost to friction — to the labour of vetting NGOs, negotiating project scopes, commissioning assessments, and managing reputational exposure when a partner underdelivers. For mid-sized companies without dedicated CSR cells, this friction is particularly punishing.

    The ZCZP route offers a regulated alternative. Companies subscribing to SSE-listed instruments are exempt from independent impact assessments — a concession that reflects the exchange’s own disclosure architecture doing the heavy lifting. Due diligence is front-loaded at the listing stage, not replicated by every corporate subscriber. The investment counts toward mandatory CSR obligations. Governance is handled by a platform, not a project manager. For a finance director staring at an unspent CSR balance in the third quarter, this is not a small relief.

    Crucially, the mechanism does not displace the 90 per cent that continues to flow through direct project implementation. It supplements it. Companies retain their flagship programmes, their employee volunteering, their community partnerships. The ZCZP window adds optionality — a credible, market-based channel for funds that might otherwise be rushed out the door in the fourth quarter with insufficient diligence.

    Why NPOs Stand to Gain the Most

    The instrument’s more transformative potential lies on the other side of the transaction. India’s non-profit sector is vast, diverse, and chronically undercapitalised at scale. Organisations doing serious work in education, healthcare, livelihoods, and climate adaptation routinely spend more time fundraising than delivering. Donor cycles are unpredictable. Government grants arrive late and lapse on technicalities. Individual philanthropy, while growing, remains concentrated in a handful of large foundations.

    Corporate CSR, directed through the SSE, offers something different: predictable, programme-linked capital with a defined horizon — typically up to three years per instrument — allowing NPOs to plan, hire, and execute with a discipline that annual grant cycles rarely permit. The absence of repayment obligation removes the distortion that debt introduces into social sector organisations, which are not structured to generate financial surpluses. And listing on the SSE — which requires disclosure norms, due diligence, and outcome reporting — is itself an institutional upgrade. An NPO that has passed exchange scrutiny carries a signal of credibility that opens doors beyond the ZCZP window.

    The SSE’s Second Chance

    The Social Stock Exchange was conceived with ambition and launched with fanfare. Its early years have been, by most candid assessments, underwhelming. Liquidity has been thin. Corporate participation has been tentative. The ZCZP instrument has existed in the regulatory framework, but without the CSR linkage, the demand side was always going to be shallow.

    The MCA amendment changes the incentive structure. Companies now have a compliance-valid, governance-sound reason to engage with the SSE. If even five per cent of India Inc’s CSR spend — roughly Rs 1,750 crore annually — is channelled through the exchange over the next three years, it would transform the SSE from an interesting experiment into a functioning market. That, in turn, would attract more NPOs to list, more investors to participate, and more intermediaries to build the infrastructure that a mature social capital market requires.

    A Note of Caution

    None of this is automatic. The 10 per cent cap is deliberately conservative — a sensible calibration for a first iteration. The risk of NPOs gaming listing requirements to access corporate capital without genuine accountability is real, and the SSE’s supervisory capacity will be tested. The exemption from independent impact assessments, while administratively convenient, should not become a licence for outcome-blindness. Companies must resist the temptation to treat ZCZP subscriptions as a CSR box to check rather than a cause to support.

    The amendment’s logic, however, is sound. It meets companies where they are — seeking compliance efficiency — and nudges them toward a more transparent, outcome-linked model. It meets NPOs where they are — seeking capital at scale — and gives them a platform that demands accountability in return. It meets the SSE where it is — searching for relevance — and gives it a demand-side catalyst it has long lacked.

    Good policy does not need to be grand. Sometimes it simply removes a friction, aligns an incentive, and trusts the market to do the rest. This amendment is that kind of policy. Quiet, well-targeted, and overdue.

  • CSR Social Stock Exchange: India opens 10% investment window for firms

    CSR Social Stock Exchange: India opens 10% investment window for firms

    The corporate affairs ministry has opened a new funding channel for nonprofits, allowing companies to direct up to 10 per cent of their mandatory corporate social responsibility spending into zero coupon zero principal instruments listed on the Social Stock Exchange, in a move aimed at deepening transparency in social sector financing.

    The amendment, effective immediately, inserts the subscription to such instruments into Schedule VII of the Companies Act, 2013 — the schedule that governs permissible CSR activities for profit-making companies required to spend at least 2 per cent of their three-year average net profit annually on social causes.

    Under the revised CSR Policy Rules, 2014, definitions for both not-for-profit organisations and zero coupon zero principal instruments have been formally introduced for the first time, providing regulatory clarity to companies seeking to deploy funds through the Social Stock Exchange.

    Not-for-profit organisations will be able to issue these instruments through the Social Stock Exchange in accordance with regulations set by the Securities and Exchange Board of India, the ministry said in a statement on Friday.

    Unlike conventional bonds, zero coupon zero principal instruments carry no interest payments and no repayment of principal, functioning instead as a regulated grant or social investment vehicle designed to fund public welfare projects.

    “It helps in furtherance of a transparent and credible mode of funding CSR projects by companies and enables social enterprises to access a wider pool of capital,” said Anshul Jain, Partner Regulatory at PwC India.

    The 10 per cent cap on CSR Social Stock Exchange investments per financial year is intended to balance innovation with fiscal discipline, ensuring core CSR commitments remain intact while creating fresh pathways for social capital mobilisation.

    The Social Stock Exchange, established under SEBI oversight, is designed to bring market discipline and disclosure standards to social sector funding — a segment historically dominated by opaque grant-making and bilateral philanthropy.

  • Sebi boosts Social Stock Exchange with NPO registration relief

    Sebi boosts Social Stock Exchange with NPO registration relief

    Securities and Exchange Board (Sebi) has boosted key rules for not-for-profit organisations on the Social Stock Exchange (SSE), extending the period during which NPO registration remains valid without fund-raising to three years from two, as it seeks to widen the fledgling platform’s reach.

    The regulator issued a circular on Wednesday outlining measures it said were aimed at promoting the SSE and facilitating fundraising for non-profits facing practical hurdles, including delays in statutory and regulatory approvals.

    Under the revised framework, an NPO may remain enrolled on an SSE for two years without raising capital through it. That window can be extended by a further year, subject to SSE approval — giving social-sector organisations more runway to ready themselves before tapping investors.

    “A NPO may register on a SSE and not raise funds through it for a period of two years from the date of registration. Such period of two years may be further extended by one additional year subject to approval by the SSE,” Sebi said.

    Sebi also slashed the minimum subscription threshold for Zero Coupon Zero Principal (ZCZP) instruments — the primary debt-like tool available to NPOs on the SSE — to 50 per cent from 75 per cent. The relaxation applies only to projects where costs and outcomes can be tracked on a clearly identifiable per-unit basis, ensuring that a partial fund-raise does not undermine project viability.

    SSEs will be required to conduct due diligence before granting in-principle approval for such partial fundraising, satisfying themselves that proceeds can be deployed meaningfully toward the stated objectives. Funds will be refunded to investors if the minimum subscription threshold is not met.

    The moves come weeks after Sebi’s board in March eased the minimum investment required from individual investors in social impact funds to Rs 1,000 from Rs 200,000, a step aimed at broadening retail participation on the SSE.

    The SSE, launched in 2022, has struggled to attract widespread participation. Analysts have cited high compliance costs and rigid fundraising conditions as barriers for smaller NPOs. Wednesday’s circular signals continued regulatory effort to unlock the platform’s potential as a mainstream social-financing channel.

  • SEBI proposes Rs 1,000 SIF investment to boost Social Stock Exchange

    SEBI proposes Rs 1,000 SIF investment to boost Social Stock Exchange

    By Eldee

    Markets regulator SEBI has proposed slashing the minimum investment by individual investors in Social Impact Funds (SIFs) to an accessible Rs 1,000 from Rs 2 lakh, in a bold move to boost retail participation and deepen the Social Stock Exchange (SSE) ecosystem.

    Issued on February 9, 2026, the consultation paper outlines reforms to make social finance more inclusive, following recommendations from the Social Stock Exchange Advisory Committee (SSEAC). The changes aim to encourage greater involvement from not-for-profit organisations (NPOs) and small investors in funding social causes.

    Key proposals include:

    • Reducing the minimum investment threshold in SIFs (which invest in SSE-registered NPO securities) from Rs 2 lakh to Rs 1,000 under SEBI (AIF) Regulations, aligning it with the existing Rs 1,000 minimum for Zero Coupon Zero Principal (ZCZP) applications.
    • Extending NPO registration validity on the SSE (without active fundraising) from two years to three years.
    • Lowering the minimum subscription requirement for ZCZP issuances to enhance fundraising ease.

    These steps build on the SSE framework operationalised since 2023 under SEBI’s (ICDR) and (LODR) Regulations, plus related circulars like the January 2026 Master Circular.

    SEBI has invited public comments on the proposals and draft circular. Submissions can be made via the online portal or emailed to consultationcfd@sebi.gov.in.

    The consultation remains open (typical 21-day period suggests comments likely due early March 2026; check the official SEBI page for the precise deadline).

  • SEBI Tightens Rules for Social Stock Exchange to Boost Transparency

    SEBI Tightens Rules for Social Stock Exchange to Boost Transparency

    Capital markets regulator SEBI introduced stricter regulations for the Social Stock Exchange (SSE) on September 19, 2025, aiming to enhance governance and transparency for not-for-profit organizations (NPOs) and social enterprises, according to a circular (SEBI/HO/CFD/CFD-PoD-1/P/CIR/2025/129).

    The updated framework mandates that NPOs registering with the SSE must be Indian trusts, societies, or Section 8 companies with a valid registration certificate held for at least 12 months. New annual disclosure requirements cover governance, finances, donor lists, and social impact, due by October 31 or the income tax return deadline, whichever is later.

    Social enterprises raising funds via the SSE must file an Annual Impact Report (AIR), verified by SEBI-registered Social Impact Assessors, covering at least 67% of program expenditure. SSEs can also enforce additional disclosure parameters to ensure compliance.

    The reforms aim to protect investors, ensure accountability, and align SSE operations with SEBI’s broader capital market regulations, such as the ICDR and LODR frameworks. By mandating independent impact assessments, SEBI seeks to drive measurable social outcomes and foster confidence in India’s growing social finance sector.

    “These changes strengthen the SSE ecosystem, ensuring funds serve genuine social purposes while maintaining regulatory oversight,” a SEBI spokesperson said.

    The rules reflect SEBI’s push to mainstream social investment while mitigating risks of fraud and enhancing credibility in the evolving social sector.

  • Social Stock Exchange gains traction, attracts diverse investors

    Social Stock Exchange gains traction, attracts diverse investors

    Notable examples include Bengaluru-based SGBS Unnati Foundation, Transform Rural India, Swami Vivekananda Youth Movement and three other organisations.

    India’s Social Stock Exchange (SSE) is gaining momentum as a platform for social enterprises and non-profit organizations (NPOs) to raise funds, attracting a growing pool of investors seeking both financial returns and social impact.

    Launched to promote inclusive growth and financial inclusion, the SSE has seen several successful listings and fund raisings.

    Notable examples include Bengaluru-based SGBS Unnati Foundation, which raised Rs 1.8 crore to train and employ government college graduates, and Transform Rural India, securing Rs 2 crore for skill development projects.

    “The SSE provides a structured way for investors to support social causes they care about,” market analyst Mahesh Kumar said. “It’s not just philanthropy; for-profit social enterprises offer potential financial returns, similar to impact investing.”

    Swami Vivekananda Youth Movement and three other organizations have collectively raised Rs 8 crore, focusing on education, health, and sustainable livelihoods.

    The SSE’s rigorous listing standards, requiring regular audited reports and independent verification of social impact claims, are attracting investors. “Transparency and accountability are key,” noted Megha Shah, an impact investor. “I can track the tangible outcomes of my investments.”

    Tax benefits recommended by the SSE committee are expected to further boost investor interest, although specific rules are yet to be defined.

    While the SSE doesn’t explicitly list top-performing stocks, its growing roster of organizations spans various sectors, reflecting India’s diverse social welfare needs.